
When installing solar panels on their home’s roof, most homeowners choose one of two payment options. They either pay the entire amount in cash or take out a solar loan.
Cash sales avoid interest payments and give the buyer immediate ownership. With a loan, you can reduce the amount you need to put down and begin repayments gradually over several years.
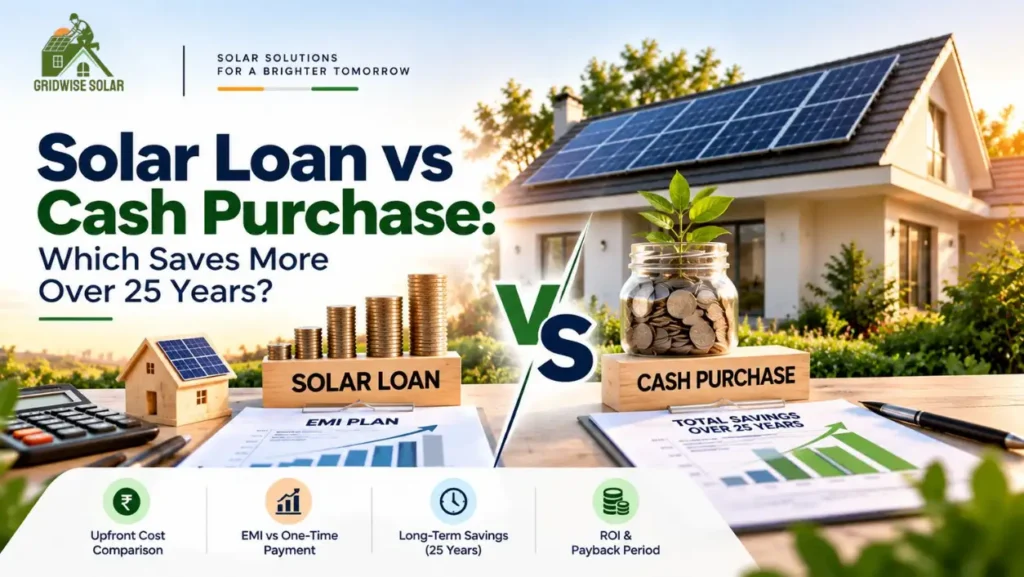
So, when comparing solar loan vs cash purchase, which saves more over 25 years? The answer depends on the system cost, loan interest, tenure, electricity savings, maintenance, subsidy eligibility, and how long you use the system
Solar Loan vs Cash Purchase: What Is the Difference?
A cash purchase means you clear the whole solar installation bill from your own savings. Once the panels go up, you face no solar EMI and no loan interest.
A solar loan lets you cover part or all of the installation cost with borrowed money. You put down some cash and then pay the rest in monthly EMIs based on the lender’s rules.
The core difference between a solar loan vs cash purchase is clear:
- Cash purchase: Bigger hit to savings up front + zero financing cost.
- Solar loan: Smaller hit to savings up front + monthly payments + interest.
Yet looking only at the monthly EMI can mislead you. You have to weigh the full sum you will hand over for the solar system under each path.
Does Paying Cash Save More Money?
If you look only at the straight purchase price, cash usually wins because it carries no loan interest or extra financing fees.
Take a home solar system priced at ₹5 lakh. Pay the full amount now, and your project cost stays at ₹5 lakh, minus any applicable subsidy or other adjustments.
Finance the same system, and you put down some money and borrow the rest. The total you repay often climbs above the original borrowed sum because of interest and other charges. But it has a downside.
Withdrawing ₹5 lakh from your savings ties up your funds for emergencies, other investments, or unexpected needs.
So cash can keep the direct solar cost lower while financing can leave you with more ready cash.
When Can a Solar Loan Make Sense?
A solar loan can work for homeowners who want solar panels without draining a big chunk of their savings at once.
Instead of paying the full project cost right away, you can spread the expense over the loan term you choose. This works well when the homeowner has steady monthly income but wants to keep savings intact.
Financing does not automatically make the solar system cheaper, though. You must check:
- Loan amount
- Interest rate
- Loan tenure
- Down payment
- Processing charges
- Total repayment amount
- Prepayment conditions
- Other applicable fees
A smaller EMI sometimes just means you pay for a longer stretch. Always look at the full repayment figure, not just the EMI the lender advertises.
What Happens Over 25 Years?
Looking out 25 years changes the whole comparison. Picture a homeowner who takes a solar loan for five or seven years. While the payments run, the panels already cut the electricity bill.
Once the loan is paid off, the EMI stops. If the solar system keeps producing well, the homeowner can enjoy the rest of the system’s life without that original solar loan payment.
With a cash purchase, you never face a loan payment, yet a larger sum left your account on day one. Long-term numbers therefore rest on more than how you paid. Real electricity output, household usage, power rates, system health, upkeep, and the rules that apply all shape the final result.
Don’t Compare Solar EMI Directly With Your Electricity Bill
A common mistake is equating the solar EMI with the monthly electricity bill and moving on.
Assume, for example, that electricity costs ₹10,000 and the solar EMI is ₹8,000. This seems like a one-time capital investment of ₹ 2,000 per month. There are times when the math doesn’t apply.
The actual electricity generated by the solar system will vary depending on the design, the roof, the weather, any shading, the equipment, and the house’s use. Your grid bill also changes based on actual usage and your billing setup.
So when you weigh solar loan vs cash purchase, keep the solar investment and financing cost in one bucket and the expected electricity savings in another.
What Does the Solar System Cost Include?
Before you decide how to pay, get clear on exactly what you are buying. A home solar setup can cover:
- Solar panels
- Inverter
- Mounting structure
- DC and AC cables
- Electrical protection equipment
- Earthing
- Monitoring
- Installation and commissioning
- Applicable documentation and approvals
Gridwise Solar fits TOPCon solar panels into its residential jobs and selects the remaining components to match the project.
In some premium home projects, panel-level monitoring or system layout may require Enphase microinverters.
This is important because there can be significant differences in value for the same size system as you will see from two quotes.
Why Solar Quotation Quality Matters
Imagine two firms both quote a 10kW system.
Regardless, one quote might feature a different set of panel specifications, inverter technology, mounting arrangement, cables, protection equipment, and installation specifications than the other.
If you compare only the final price, you may not be comparing equivalent systems. Before taking a loan or paying cash, ask the installer for a detailed quotation showing the major components and scope of work.
For homeowners seeking solar installation in Delhi NCR, this step shows exactly what the money is buying.
Cash vs Solar Loan: Quick Comparison
| Factor | Cash Purchase | Solar Loan |
| Upfront payment | Higher | Lower |
| Loan interest | None | Applicable |
| EMI | None | Yes |
| Liquidity after purchase | Lower | Higher |
| Financing charges | None | May apply |
| Total project cost | Usually lower | Can be higher |
| Ownership | Immediate | Subject to financing terms |
| Main advantage | Avoids borrowing cost | Spreads upfront expense |
Neither path suits every homeowner automatically. Your savings balance, monthly cash flow, loan terms, and other money goals all need to sit at the table.
What Should Homeowners Check Before Financing Solar?
Whether you pay cash or take a loan, first confirm the system itself is sized and built right.
A solid solar company in Delhi NCR will study your electricity use and roof before suggesting a capacity.
The same check applies when you look at a solar company in Delhi, solar company in Noida, solar company in Gurgaon, solar company in Ghaziabad, or solar company in Faridabad.
Ask:
- Why has this system capacity been recommended?
- Which TOPCon panels are included?
- Which inverter will be installed?
- What mounting structure is being used?
- What electrical protection is included?
- What warranties apply?
- Is installation included?
- Who handles commissioning and documentation?
- What after-sales support is available?
Only after you understand the full system should you compare payment options.
Gridwise Solar: Quality Installation Before Financing
Gridwise Solar designs home solar systems around the actual property instead of pushing a fixed package.
The team looks at electricity use, usable roof space, shade, system size, and installation needs before locking in the final setup.
Gridwise fits TOPCon solar panels into its residential work and pairs them with the right inverter technology, mounting structures, branded cables, electrical protection, and other needed parts.
Homeowners also get help through the wider process—system design, installation, testing, commissioning, and the paperwork that goes with it.
This order matters because you should choose a payment option only after you know the exact solar system you are buying.
So, Solar Loan or Cash Purchase?
So, where to go solar loan vs cash purchase? If you have enough savings and want the lowest upfront cost, paying cash will save you interest and additional financing charges.
If cash is more important, a solar loan can spread the initial cost over a number of years. However, consider the total repayment amount and make sure the EMI fits your budget.
The plain comparison looks like this:
Cash option = total upfront solar cost
Loan option = down payment + total EMIs + financing charges
Then factor in the solar benefits you expect over the system’s working life.
No single answer fits every home because the result turns on your real project cost and the loan terms you get.
Conclusion
Decide on a solar loan vs cash purchase only after you know the full solar installation price and the financing details.
Cash purchase skips interest and keeps the direct cost of owning the system lower. A solar loan lightens the money you need to put down now and leaves more cash free.
For homeowners planning solar installation in Delhi NCR, begin with a full system proposal. Get clear on the TOPCon panels, inverter, mounting structure, electrical parts, installation scope, and warranties before you choose how to pay.
Gridwise Solar builds custom home solar setups with TOPCon panels and handles the full solar installation in Delhi NCR.
Ready to plan your home solar investment? Reach out to Gridwise Solar for a custom proposal and compare cash purchase with financing options before you decide.